MONTHLY NEWSLETTER – SEPTEMBER 2026
October 1, 2026 |
Download Document
A summary of key events and market trends during the month of September
Global Markets Updates
- The US midterm elections on 3 November will determine control of Congress and could bring increased market volatility as investors assess the implications for taxation, spending and regulation. A Republican hold would leave a clearer path for the administration’s legislative agenda, while Democratic control of either chamber would introduce greater constraints. Neither outcome should be treated as automatically positive or negative for equities. One issue we are watching closely is the buildout of AI data centres. Concerns about electricity and water bills, alongside local disruption, extend across party lines, making state and local decisions important alongside the congressional result. For investors, the practical question is whether these pressures delay projects or raise their costs.
- Results released during July–September, largely covering the second quarter, offered an encouraging picture of corporate profitability. By mid-September, more than 80% of reporting S&P 500 companies had exceeded earnings expectations. Technology remained an important driver, but positive surprises also extended to energy, financials, industrials and materials. Some headline profits benefited from investment gains, however, making it important to distinguish operating progress from accounting effects. For the July–September operating quarter itself, most results are still ahead. Analysts currently expect approximately 29% year-on-year growth in S&P 500 earnings, although that remains a forecast rather than a reported outcome.
- The latest AI developments point towards systems designed to complete complex work, rather than simply answer questions. On 30 September, Google announced Gemini 4 Argon, targeting software engineering, financial and legal workflows, and cybersecurity. Initial access is restricted to selected cyber defenders while the company continues safety testing. Also this week, Synopsys and OpenAI announced a partnership to develop GPT-Synopsys, a specialised model intended to operate chip-design software and help engineers optimise and verify semiconductor designs. This is a development programme, rather than an already-proven commercial product, but it illustrates how AI could become embedded in highly valuable professional workflows.
- The US IPO pipeline remains substantial, but the timetable has become less predictable. Anthropic is a prominent prospective listing, with recent reporting pointing to a possible November debut rather than earlier autumn plans. OpenAI has pushed its offering into at least 2027, with management saying it wants greater confidence in safety before proceeding. Other names worth monitoring include AI cloud provider NScale and data-centre developer SB Energy, although SB Energy has delayed its offering and NScale’s timing remains uncertain. For investors, a more selective market can be constructive if it encourages realistic pricing. We will assess new offerings on revenue quality, funding requirements, governance and valuation, rather than brand recognition or first-day enthusiasm. Patience remains appropriate while terms and financial disclosures develop.
US MIDTERM ELECTIONS UPCOMING
The US election cycle inevitably leads to some volatility around the event, and we expect this time to be no different.
Key among policy debates will be developments in the world of Artificial Intelligence from the construction of data centers to safety and core alignment issues.
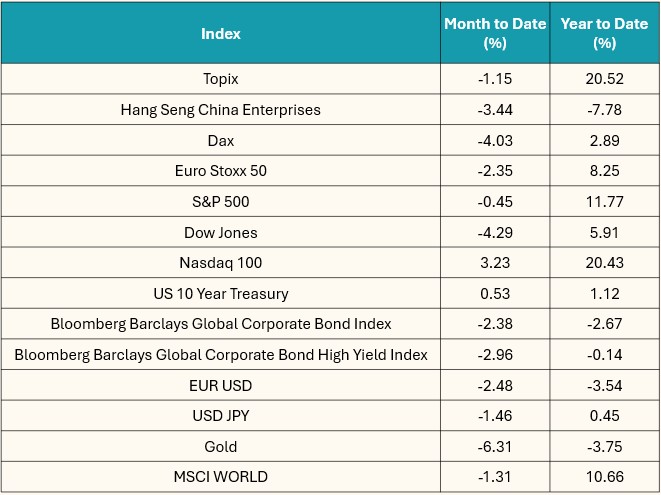
Key Markets
SGMC Forward Views
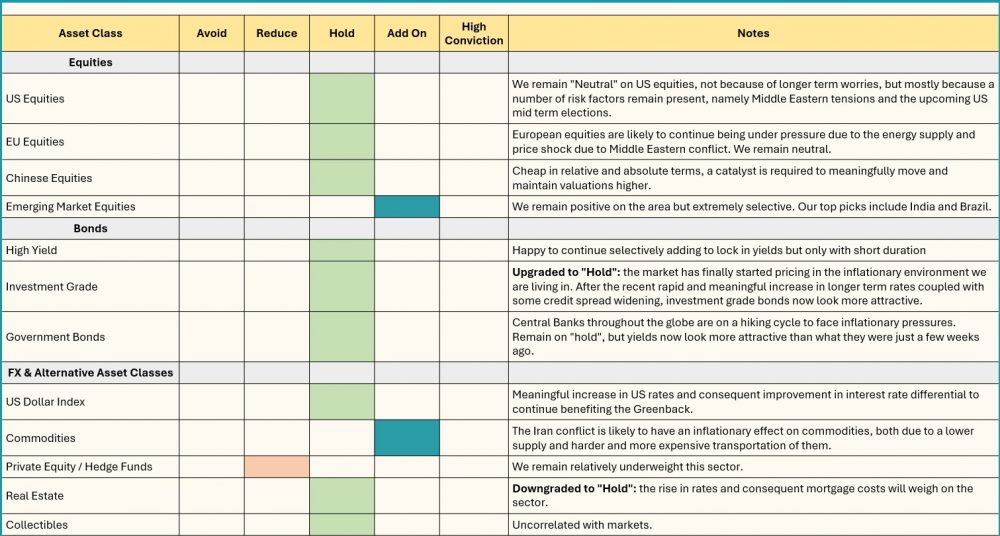
- Upgraded Investment Grade Bonds from Reduce to Hold: the market has finally started pricing in the inflationary environment we are living in. After the recent rapid and meaningful increase in longer term rates coupled with some credit spread widening, investment grade bonds now look more attractive.
- Downgraded Real Estate from Add On to Hold: the rise in rates and consequent mortgage costs will weigh on the sector.