MONTHLY NEWSLETTER – OCTOBER 2026
November 1, 2026 |
Download Document
A summary of key events and market trends during the month of October
Global Markets Updates
- With the US midterm elections taking place on November 3, markets are entering the vote with measured anticipation rather than a singular political bet. Republicans currently hold narrow majorities in both chambers; any change in control would alter legislative oversight and fiscal negotiations, while continued Republican control would offer greater policy continuity, at least initially. For investors, the principal questions concern 2027 budget and debt-ceiling discussions, the direction of financial and technology regulation, and state decisions affecting AI data-centre development. Yet the election does not reset the economic cycle.
- Federal Reserve policy, corporate earnings, interest rates and the returns on AI-related capital expenditure are likely to remain more consequential for equity and bond valuations over time. Some short-term volatility is possible as results clarify the balance of power, but investors would be well served by distinguishing concrete policy changes from political headlines rather than repositioning portfolios solely around election-night outcomes.
- Third-quarter results from US technology companies have generally confirmed robust underlying demand, particularly for cloud computing, AI infrastructure and digital advertising. Microsoft, Alphabet and Amazon reported strong cloud growth, while selected enterprise software companies also demonstrated resilient customer spending.
- However, the scale of AI-related capital expenditure has become a more prominent concern, with rising infrastructure commitments weighing on free cash flow at several large platforms. Investor reactions have consequently been more selective, rewarding evidence of sustainable monetisation rather than revenue growth alone. Overall, the earnings season suggests that technology fundamentals remain healthy, although expectations for investment returns are becoming increasingly demanding.
- The Federal Reserve’s outlook has shifted toward maintaining restrictive monetary policy for longer. Having raised rates in September, the Fed held its benchmark range at 3.75–4.00% in October, citing resilient growth and still-elevated inflation. Markets and economists broadly anticipate another increase in December, while the Fed’s September projections suggest rates could remain broadly unchanged through 2027. Strong investment spending and a stable labour market give policymakers room to proceed gradually, although weaker employment or faster disinflation could change that assessment. For investors, the central consideration is increasingly the duration of elevated borrowing costs rather than an imminent easing cycle.
- Apart from the US midterms, the Initial Public Offering from Anthropic will be a key event for global investors as it will signal the readiness, or not, of investors to incrementally fund allocations to bring AI tech to production at scale.
GLOBAL MARKETS PAUSE ON MULTIPLE FRONTS
With the US Elections imminent, markets look closely to the results and the likely impact on leading stocks on account of a change in the composition of the US Congress
Larger capital expenditure bills at the Hyperscalers have caused some investors to lighten up exposure to the AI theme. At the same overall demand for compute and tokens continues at pace.
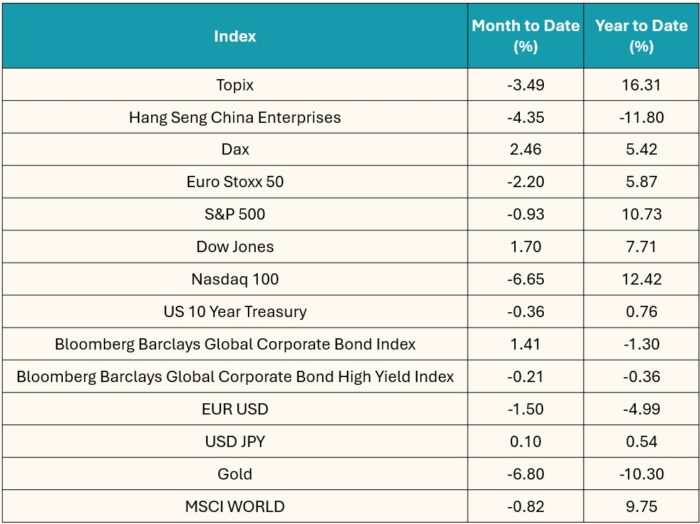
Key Markets
SGMC Forward Views
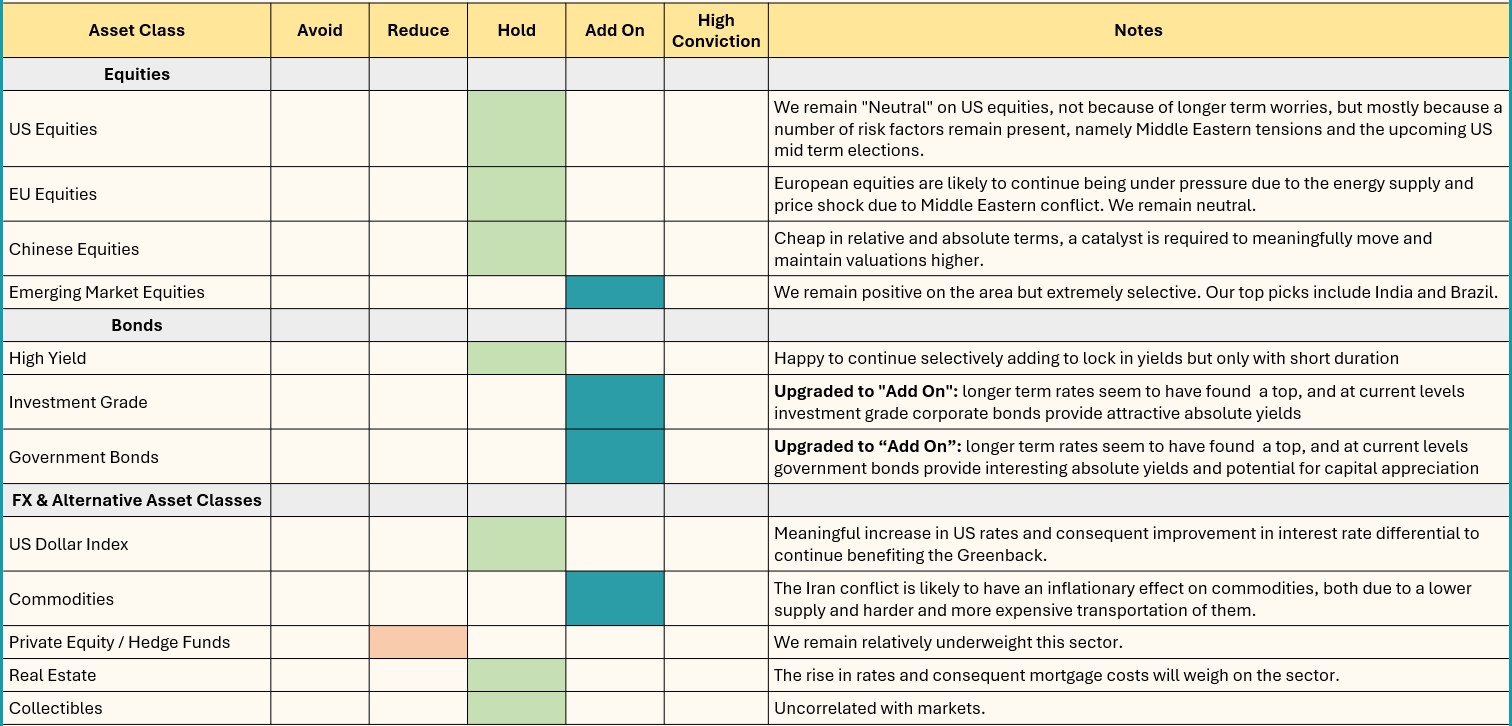
- Upgraded Investment Grade Bonds from Hold to Add On: longer term rates seem to have found a top, and at current levels investment grade corporate bonds provide attractive absolute yields
- Upgraded Government Bonds from Hold to Add On: longer term rates seem to have found a top, and at current levels government bonds provide interesting absolute yields and potential for capital appreciation